Proprietary databases
We organise historical and current market information in our own data environment, with attention to quality, consistency and reproducibility.
INDEPENDENT INVESTMENT COMPANY · UDDEVALLA, SWEDEN
We combine proprietary data infrastructure, financial research and disciplined portfolio optimisation across global equities, exchange-traded funds and currencies.
Explore our company SEH UDDEVALLA, SWEDEN
Sweden Equity Holding, aktiebolag is a technology-driven investment company based in Uddevalla, Sweden. We research quantitative approaches to financial markets and develop the data systems and portfolio analytics that support our own investment decisions.
Our work combines empirical research with practical market experience. By connecting proprietary databases, portfolio analysis and transaction reconciliation, we can examine how each decision is formed, tested and implemented.
We maintain proprietary databases, engineer features from market data and develop models that translate research into systematic decisions.
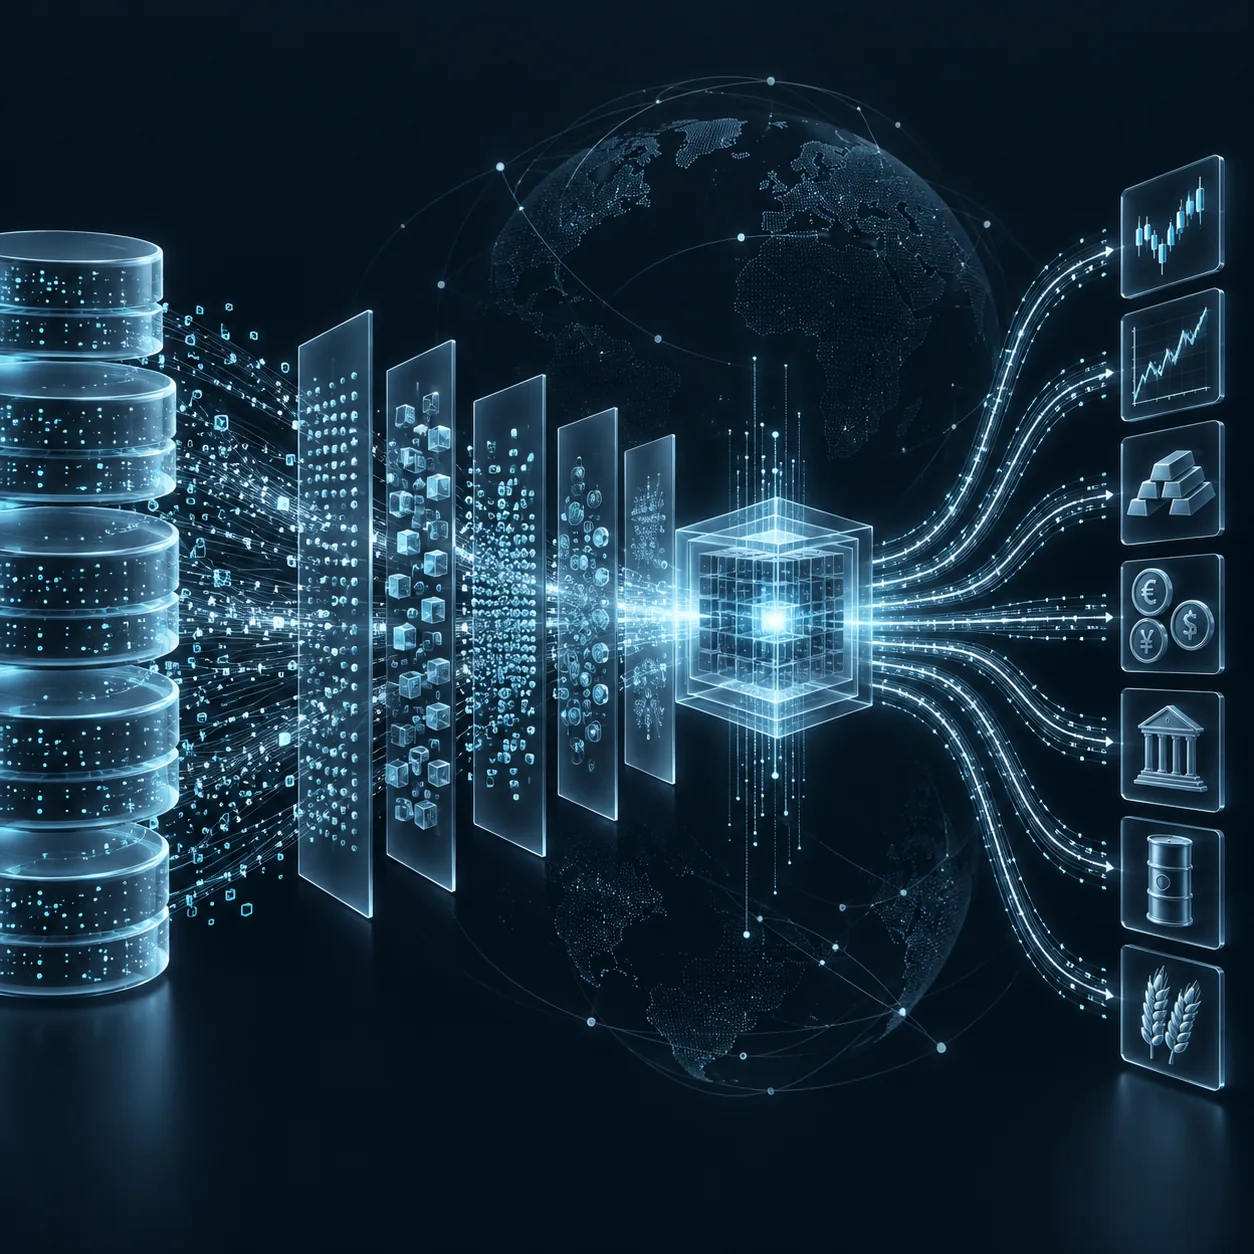
We organise historical and current market information in our own data environment, with attention to quality, consistency and reproducibility.
We create and test proprietary features that describe price behaviour, liquidity, volatility and relationships across instruments and markets.
We evaluate historical returns, volatility and diversification within an explicit investment policy, testing how allocations respond to changing market conditions.
Connected portfolio and accounting systems support systematic monitoring of holdings, cash and transactions. Investment decisions and trade execution remain subject to human review.
We invest across international equity and bond markets through a focused portfolio of equities and exchange-traded funds. We review liquidity, geographic exposure and concentration alongside the relationships between our holdings.
Our current mandate uses an unleveraged portfolio with explicit limits for asset classes, individual holdings and volatility. Historical analysis supports allocation decisions, while outcomes remain subject to market conditions.
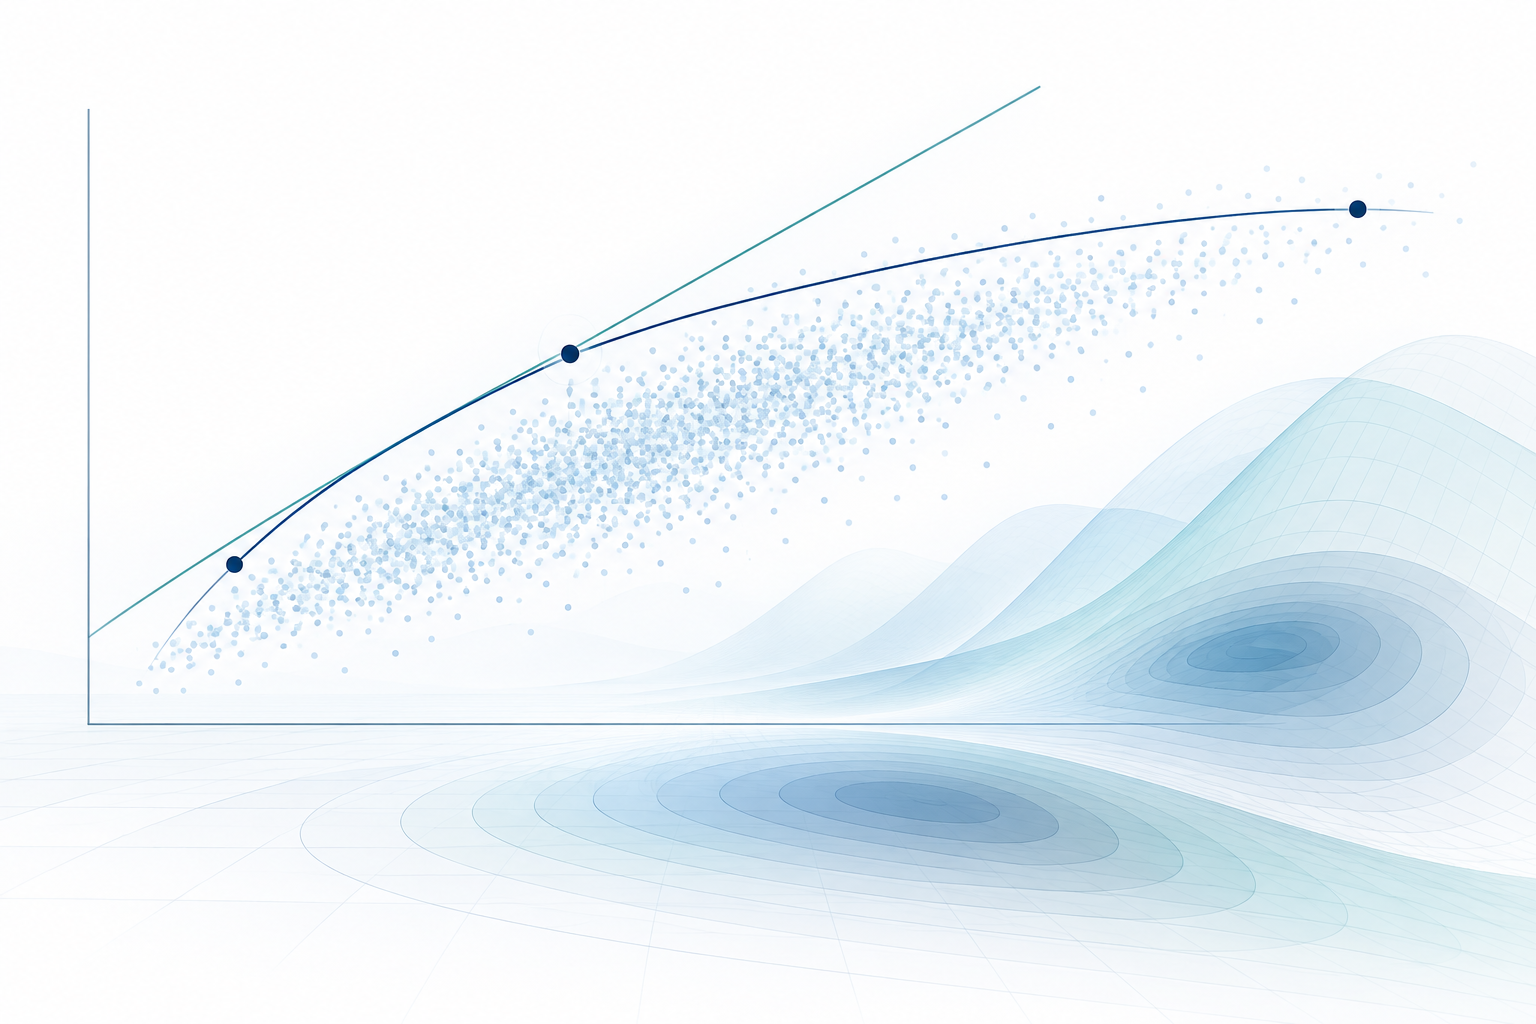
We apply modern portfolio theory to optimise how capital is allocated across our holdings. By analysing expected returns, volatility and the relationships between assets, we seek a disciplined balance between risk and opportunity. Our optimisation is guided by explicit investment limits, diversification requirements and trading costs, with allocations reviewed as market conditions evolve.
Historical estimates inform our decisions; they do not guarantee future returns.
Select an exposure group to view its portfolio share. Europe is a shared IPS regional allocation, not a separate weight for each highlighted country. Global exposure is shown separately.
Follow our IBKR investment portfolio through a cash-flow-adjusted index. The series starts at 100%: a rise to 200% represents a cumulative return of 100%. Deposits and withdrawals are excluded from investment performance.
INDEXED PORTFOLIO NAV · SEK BASIS
—Loading verified daily observations…
Connecting to the published performance series.
This is the performance of our IBKR portfolio, not the full net asset value of Sweden Equity Holding, aktiebolag. It excludes assets, liabilities and company expenses outside the account. No capital amounts, positions or account identifiers are published.
Daily, broker-reported time-weighted returns are compounded geometrically: index = 100 × ∏(1 + daily return). The index reflects the account’s reported return treatment, including items recorded in that account. It is not an independently audited performance record or a claim of GIPS compliance.
Volatility and diagnostic ratios use 252 observations per year and require at least 63 observations. Skewness and excess kurtosis are bias-corrected. The latest-return z-score uses the preceding 63 observations. VaR and CVaR are one-day historical loss estimates with a minimum of 250 observations; even then tail estimates are uncertain. No missing returns are filled or simulated.
Sharpe uses a zero risk-free rate and Sortino a zero minimum acceptable return; neither is an excess-return comparison against current interest rates. Negative historical VaR denotes a positive return threshold, not a guaranteed gain. Undefined ratios are not shown as zero.
Statistics use the entire published history, independently of the chart-period selection. Past performance does not predict future results. This page describes our own investment activity and is not an offer or an investment recommendation.
| Date | Index | Daily return | Drawdown |
|---|
For enquiries about our company, research or activities, please get in touch. We welcome thoughtful conversations about data, technology and financial markets.